 TEXTILES.ORG


Any successful business eventually catches the eye of potential buyers. However, a good sale can only happen if the company is strong beyond the surface level. A viable succession plan is a powerful way to build resilience and strengthen the company’s continuity.
“Some people think succession planning is a cut-and-dried process where you sell the business on Friday and walk out the door on Monday,” says Steve Frost, former CEO and current senior advisor of Stamford Tent & Event Services in Stamford, Conn. “It’s a lot more than that.”
For more than five decades, Frost led Stamford Tent & Event Services, which provides tent rentals and sales in Connecticut, New Jersey and Long Island, N.Y. In January 2026, New York Tent (through its parent company Aspire Event Group LLC) acquired the business.
The succession planning process that led to this transition took multiple years. “Without succession planning, businesses like Stamford Tent usually go to auction,” Frost says. “We looked at this option, but then I’d have a team of 100+ people who would be out of a job in a week. That didn’t fit with our mission and value statement to do the right thing.”
Various private equity firms had contacted Frost almost monthly to inquire about buying the company. When one private investor approached Frost, his offer was so attractive that Frost accepted. “But then we found out this buyer wasn’t going to make any capital investments in the business for three years. That didn’t sit well with me, because we put at least 10% to 15% of gross income into new equipment each year.”
Frost was so concerned that he backed out of the deal. “The guy couldn’t believe it, but I couldn’t do that to my employees. There’s a legacy involved here.”
An unexpected twist developed when a competitor, David Tannenbaum, approached Frost about selling Stamford Tent to New York Tent. “My first reaction was, ‘Are you nuts?’ Why would I expose all my financials to a competitor?” Frost says.
Still, he was willing to talk and explore some potential options — and so were his family members who had stakes in the business. “Building trust takes time, and this was a two-year dance,” Frost says. “The more we worked with David, the more we realized how much we had in common.”
Preparing for the future
Succession planning is much more than signing legal documents. “It’s about protecting what you’ve built,” says Avi Olitzky, president and principal consultant of Olitzky Consulting Group LLC. “Your business isn’t just an asset — it’s a legacy.”
Many business owners avoid succession planning, however. “If you don’t make time for succession planning, the business will likely be shaped at some point by a crisis, like an illness, death or a surprise departure,” Olitzky says.
Frost has experienced this. In 1967, his father, Donald, purchased Stamford Tent when it was a tiny business with two trucks and five employees. After Donald died of cancer in 1971, Frost’s mother tried to sell the business.
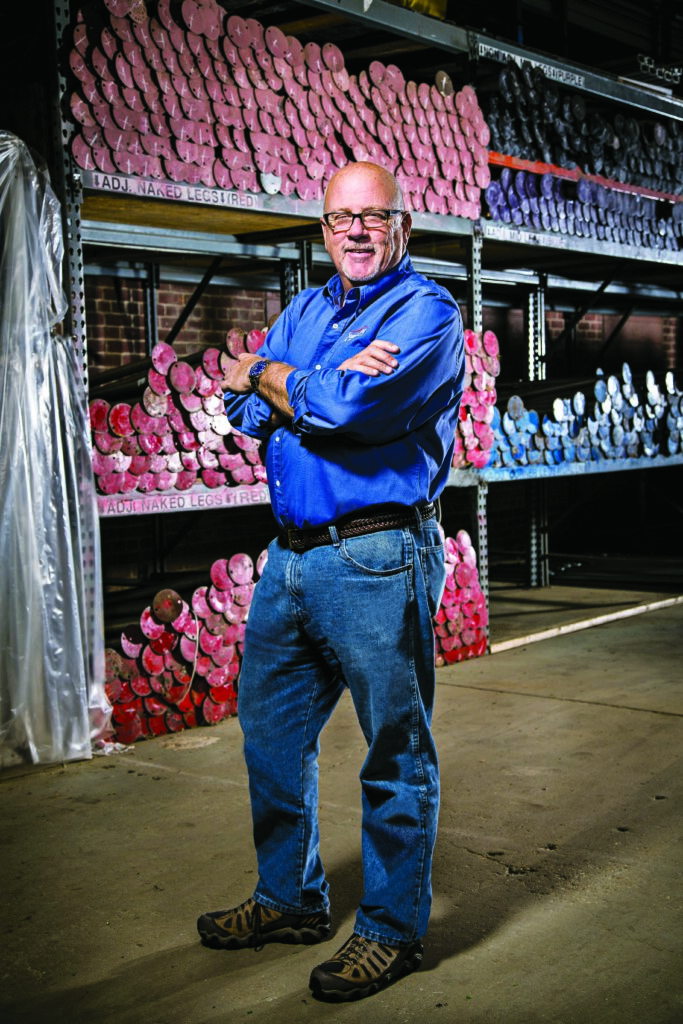
When she suggested putting it up for auction, then-18-year-old Frost saw an opportunity. “I’d been roofing houses in Florida for $2.50 an hour and was frustrated with a career that was going nowhere,” he says. “I decided to try the tent business for a year.” The business thrived under Frost’s leadership, and it grew as he acquired competitors.
While Frost averted a potential business succession crisis, other companies aren’t so fortunate. Some business owners struggle with succession planning because they don’t know where to start, Olitzky says. Others fear they’ll become irrelevant if they aren’t in control anymore.
“Conversations about succession planning often feel too complex, too personal, too final,” Olitzky says. “When succession planning feels overwhelming, that’s usually because you’re trying to solve too much, too fast.”
It typically takes a period of years, not months, to develop a practical, workable succession plan. Olitzky offers the following tips:
• Lower the emotional temperature. “Succession planning isn’t about pushing someone out,” Olitzky says. “Don’t begin with, ‘Who’s your successor?’ Start by discussing ways to incorporate more resilience into the business.”
• Recognize that issues won’t be solved in one meeting. Olitzky recommends spending two to four months on “succession discovery.” Explore what’s working well with the business, conduct an audit to determine where the business is vulnerable and discuss goals for the future.
• Reframe the issues. Begin with “what if” questions: What if the current CEO is unexpectedly unavailable for 30 days? Who will lead the company? Who can write checks? “When you ask people these ‘what if’ questions, you’ll see the light bulb go on,” Olitzky says. “The answers will help you separate the pieces to develop a succession plan.”
• Explore all your options. Don’t assume the company automatically will pass to the next generation of family members. Frost began seriously thinking about succession planning when his oldest son was a college senior. “He had worked here during summer breaks,” Frost says. “We had some frank conversations, and my son made it clear he wasn’t enough of a ‘people person’ to want this business.”
• Work with advisors. Trusted outside voices are essential in succession planning. “Succession planning requires some tough conversations that people inside the company should not have to lead,” Olitzky says. “Involve skilled outside advisors.” Advanced Textiles Association can be a resource to find these advisors, he adds.
• Prepare for resistance. Succession planning is rarely a streamlined process. “When there’s resistance, don’t panic,” Olitzky says. “The more questions you ask, you’ll often discover people are stressed about money issues, power/control or other concerns.” Don’t argue with resistance, he adds. “The goal is to lower people’s defensiveness. When you meet resistance, slow things down.”
• Develop a workable timeline. Succession planning works best when it’s a multiyear process. After the succession discovery process is complete, Olitzky recommends a planning and alignment phase to craft the succession road map. This can take three to 12 months. Then comes the actual transition, which takes one to three years. Let the successor start leading meetings and making some key decisions. “Gradually let go of control,” Frost says. “Give your successor time to learn from any mistakes they might make and have time to recover.”
• Be patient and flexible. Succession planning isn’t a linear process. “There are moments of clarity followed by moments of resistance,” Olitzky says. “It requires patience, structure and a willingness to return to the same questions to move forward.”
• Plan for post-transition support. This can take six to 18 months, Olitzky says. After signing a deal with New York Tent, Frost began a transition period where he served as a consultant for six months. While Frost retired June 30, his brother, Tim, and Brian Rieke, a valued Stamford employee who had become a part-owner of the company, agreed to stay on. Rieke also retained an ownership stake in Aspire.
“I’m proud to see Stamford Tent enter its next chapter with Aspire and New York Tent,” says Frost, who looks forward to traveling with his wife. “A successful transition means knowing that when I leave, the people who are still there will prosper.”
Darcy Maulsby is a freelance writer based in Lake City, Iowa.